A Hair Salon Pricing Guide for Garner, Clayton & Johnston County Salon Owners
If you’re pricing out hair salon insurance cost for the first time, or trying to figure out why your renewal went up, you’re not alone. Salon owners across Garner, Clayton, and the rest of Johnston County ask us this question every week. The honest answer is that it depends on your salon’s size, staffing setup, and the services you offer, but we can give you real ranges and the specific factors that move the number up or down.
What does hair salon insurance cost in North Carolina?
Most small, single-chair salons in North Carolina see business owner’s policy (BOP) pricing somewhere between $500 and $1,500 per year, while larger salons with multiple stylists, more square footage, and additional services like coloring, extensions, or waxing often land between $1,500 and $3,500 or more annually. These are ballpark figures, not quotes. Your actual premium depends on where your business is located in Johnston County, how many people work there, your claims history, and the carrier writing the policy. We can’t promise a specific number until we run your details, but these ranges give you a realistic starting point for budgeting.
What factors affect beauty salon insurance cost in NC?
Several specific things push your premium higher or lower, and most of them are within your control. Here’s what carriers actually look at:
-
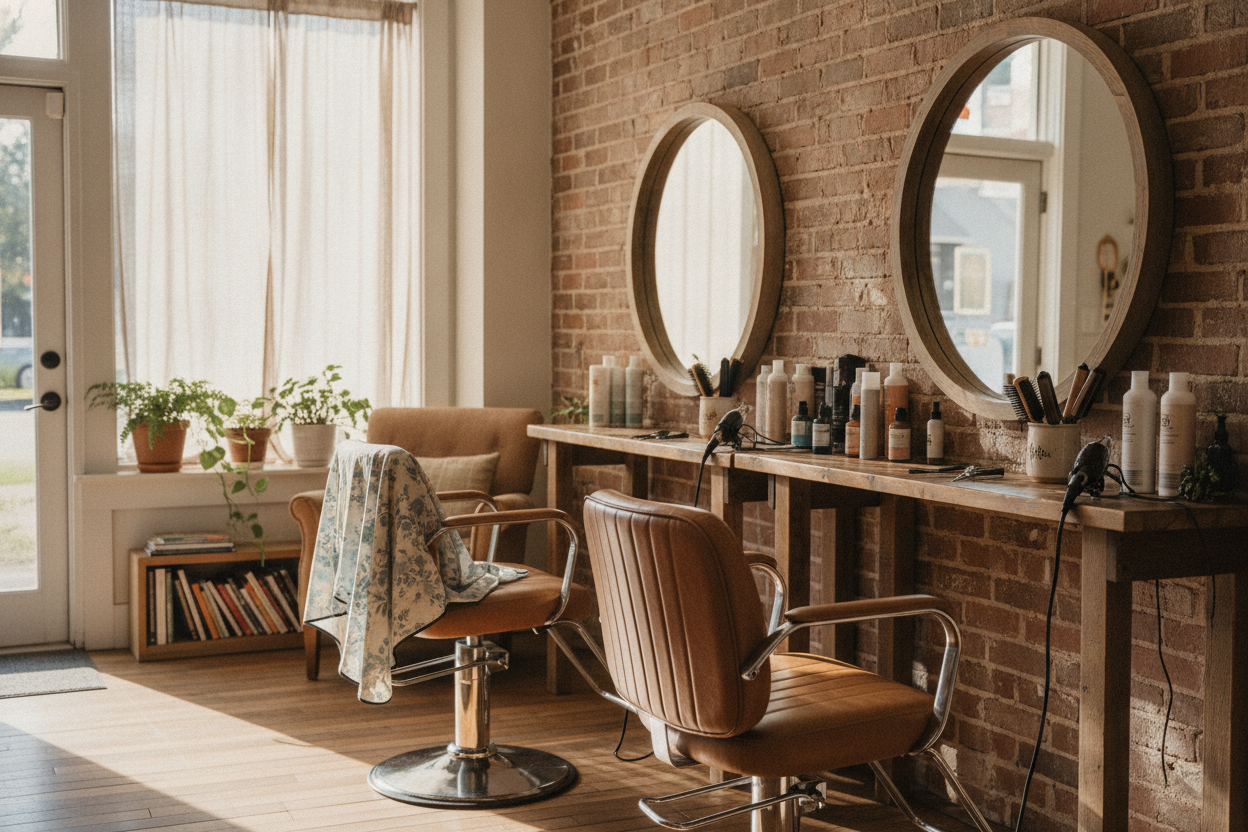
Number of chairs and stylists. More chairs and more staff mean more foot traffic and more exposure, which typically raises the base premium.
-
Booth rental vs. employee model. A salon with W-2 employees carries different liability than one where stylists rent their own booths and operate as independent contractors. We’ll cover this in more detail below.
-
Services offered. Basic cuts and blowouts carry less risk than chemical services like perms, relaxers, or keratin treatments. If your salon offers extensions, microblading, or piercings, expect that to factor into pricing.
-
Square footage and location. A larger space in a busy shopping center may cost more to insure than a small studio, partly due to property values and partly due to local risk factors.
-
Claims history. If your salon or a previous business you owned has a history of liability or property claims, that history can affect your rate.
-
Building ownership. If you own your building instead of leasing, you’ll need property coverage on top of your liability coverage, which changes the overall BOP price.
What’s included in a salon BOP price?
A business owner’s policy bundles general liability and commercial property coverage into one policy, and that bundle is usually the foundation of your salon BOP price. General liability protects you if a client slips on a wet floor or has an allergic reaction to a product used in your salon. Property coverage protects your chairs, mirrors, styling tools, and the physical space itself if there’s a fire, storm damage, or theft. Many salons add business interruption coverage to that BOP, which helps replace lost income if you have to close temporarily after a covered event. Depending on your services, you may also want to layer on professional liability or product liability coverage, since a standard BOP doesn’t always cover claims related to a botched chemical treatment or a defective product you sold or used.
Does booth rental change your insurance needs?
Yes, booth rental changes who needs to carry what coverage. If you own the salon and rent chairs to independent stylists, your policy typically covers the building, common areas, and your own liability as the property owner, but each booth renter is generally responsible for carrying their own liability insurance for the services they perform. If you employ stylists directly instead, your salon’s policy usually needs to extend liability coverage over their work as well, along with workers’ compensation in most cases. This distinction matters a lot when you’re comparing salon BOP price quotes, because a policy built for an owner-operator model won’t automatically protect a booth-rental arrangement the same way. We walk through this with every salon client so there’s no gap in coverage on either side.
What specific risks should salon owners plan for?
Salons face a handful of recurring risks that are worth planning for directly. Slip-and-fall incidents are common given wet floors, hair clippings, and foot traffic near sinks and styling chairs. Chemical treatment reactions, whether from color, relaxers, or keratin services, can lead to liability claims if a client has an adverse reaction. Equipment damage or theft, especially with expensive styling tools and electronics, is another everyday risk. And if you store client payment information or run appointment software, cyber liability is worth a conversation too. None of this is meant to alarm you, it’s just the reality of running a business that works directly with people’s skin, hair, and scalp, and it’s exactly what the right policy is built to handle.
Why work with an independent agency for salon insurance?
We’re an independent insurance agency, which means we’re not tied to one insurance company and can shop your salon’s coverage across multiple carriers, including Erie Insurance, to find a fit that matches your actual risk and budget. That matters for salon owners because coverage needs vary so much between a one-chair studio and a ten-station salon with booth renters and retail sales. Your needs are unique, and we’d rather take the time to understand your setup than hand you a one-size-fits-all policy.
Trusted by salons across Garner, Clayton, and Johnston County
We’ve worked with salon owners throughout Garner, Clayton, and greater Johnston County long enough to know the local business landscape, from strip-mall studios to standalone salons on Main Street. Many businesses in this community trust Bailey Insurance Agency to protect what they’ve built, and salon owners are no exception. We’re here for you every step of the way, not just when the policy is signed, but when questions come up later about a new hire, an added service, or a renewal that doesn’t look right.
The bottom line for salon owners
-
Expect a small salon Business Owner Policy to run roughly $500–$1,500 a year, with larger or multi-service salons often landing between $1,500 and $3,500 or more.
-
Chairs, staffing model, services offered, and claims history all move your price up or down.
-
Booth rental and employee-based salons need different coverage structures, so don’t assume one policy fits both.
-
A BOP covers the basics, but chemical services, product sales, and cyber exposure may call for additional coverage.
For the full picture on coverage options built specifically for salons, visit our beauty salon insurance page for a complete breakdown of what’s typically included and what’s optional.
Ready to see what coverage looks like for your salon? Contact us for a free quote or to discuss your coverage options, and we’ll help you make an informed decision about protecting what matters most, your salon, your staff, and the business you’ve worked hard to build.